

Acima Leasing

- 2.24K Reviews
- 3.8
- Downloads
- 1,000,000+
Our take on Acima Leasing from Appgk
When I first opened Acima Leasing, I understood its appeal quickly: it is a finance app built around a no-credit alternative to traditional financing. That makes it interesting for someone who needs an item now but does not want to use, or cannot rely on, a conventional credit route. At the same time, I would not treat it as a shortcut to cheap borrowing. The useful question is not simply whether I could complete an application, but whether the payment arrangement fits my budget after I understand the total commitment.
Acima, the developer, has made the app free to install, and it is listed for Everyone. It belongs to the finance category rather than shopping or banking, so I approach it as a tool for arranging a lease-to-own style purchase, not as a general wallet for everyday money management. That distinction matters from the first screen: the app is most relevant when I already have a specific purchase in mind.
The app has reached over a million installs, with a 3.8 average from around five thousand ratings and roughly two thousand reviews. Those figures suggest that plenty of people find it useful, but they also remind me to keep expectations realistic. A finance app can work smoothly while the underlying offer still needs careful consideration.
Getting from installation to a useful first result
What to expect before starting
I would begin by deciding what problem I am trying to solve. If I need a particular household item, appliance, electronic device, or another eligible purchase and traditional financing is not practical, Acima Leasing may be worth investigating. If I am only browsing or hoping the app will provide unrestricted cash, it is probably the wrong starting point.
Best Parts of Acima Leasing
Things to Keep in Mind About Acima Leasing
The app’s central value is access to an alternative financing path. That does not automatically mean approval, a lower total cost, or a better deal than paying upfront. I would compare the complete payment obligation with the item’s cash price and with other available choices before accepting anything. The monthly or scheduled amount can look manageable while the full cost tells a different story.
For a first-time user, the most reassuring approach is to treat the app as a guided application and account tool. I would have my personal details ready, use information that matches my records, and read every screen instead of tapping through quickly. Financial applications reward accuracy more than speed.
News and Features Related to Acima Leasing

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
One practical tip is to install it when I have time to finish the process calmly. Starting while standing in a store, rushing through checkout, or using a weak connection creates avoidable pressure. I prefer to review the item, the payment terms, and the identity details in one sitting, then save any confirmation shown inside the account.
Setting up an account without creating confusion
The first setup should be approached like any other financial service. I would use an email address and phone number that I can access reliably, choose a password I do not reuse elsewhere, and check that names and contact details are entered consistently. Small mismatches can become frustrating later if I need to verify an application or recover access.
Don't want to read the full review?
I would also pay attention to the difference between creating an account and receiving an offer. Registration gives me a way to use the service; it should not be interpreted as a promise that every purchase will be approved on the terms I want. Keeping those two steps separate makes the experience easier to understand.
The current version is 5.3, and the app supports Android 7.0 and later. That broad compatibility is helpful if I use an older Android phone, although I would still keep the operating system and the app updated when possible. Finance apps are not ideal candidates for running indefinitely on an outdated device, especially when login and security are involved.
Screenshots
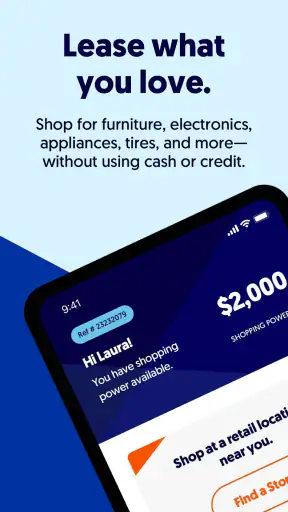
During setup, I would avoid entering information while distracted and would double-check the final review screen. My best habit here is to pause before submitting: confirm the requested amount or item, inspect the contact details, and make sure I know where the app will display the next step. This takes less time than correcting an avoidable mistake.
The first meaningful success
For me, the first successful action is not merely opening the app or creating a profile. It is reaching a clear, understandable result for a real purchase: either seeing the next application step or learning what information is needed to continue. That gives the app a purpose and prevents me from treating it like a vague promise of financing.
A realistic example would be replacing a broken appliance. I would first identify the exact product and its cash price, then use Acima Leasing to explore the available route rather than applying blindly. If the app presents an offer, I would record the payment schedule and total obligation before discussing the purchase with the retailer. If it does not move forward, I would regard that as useful information and compare other options instead of repeatedly submitting applications without a plan.
The strongest workflow is to keep the app open while I have the purchase details nearby, but not to let a sales conversation rush my decision. I would ask myself three simple questions: Can I afford every scheduled payment? What will the item cost in total through this arrangement? Is there a cheaper way to obtain it, even if that means waiting?
This is also where the app differs from a normal credit-card purchase. A card may offer a familiar revolving account, while Acima is designed around a specific no-credit financing alternative. That can help someone who does not fit a conventional credit process, but it may be less attractive for a person who can pay cash or already has a genuinely low-cost financing option.
Where first-time users may hesitate
The biggest source of confusion is likely the word “alternative.” No-credit does not mean no financial responsibility, no screening, or no cost. I would never read that positioning as “free money.” The arrangement still needs to be understood as a commitment connected to a purchase, and the consequences of missed or unaffordable payments matter.
Another common misunderstanding is comparing only the recurring payment. I find it safer to write down the item’s cash price beside the complete lease-to-own obligation. If I cannot identify the total amount clearly, I would stop and seek clarification before accepting the offer. A convenient interface should not replace careful reading.
Users may also confuse the app with a bank account, credit score monitor, or general budgeting service. I would not install it expecting tools for tracking all household spending. Its usefulness is narrower: it helps with the Acima financing journey. That focused purpose is a strength when I have a qualifying purchase, but a limitation when I want broad personal-finance management.
Approval questions can create another point of uncertainty. I would not assume that installing the app guarantees eligibility, nor would I assume that a declined request means the app is broken. Eligibility depends on the application and purchase context. If the result is not suitable, I would compare alternatives rather than repeatedly trying to force the same transaction.
Using the app responsibly after the first result
Once I have a meaningful result, my next step would be documentation. I would keep the agreement details, payment dates, item information, and any confirmation available to me. I would also set a personal reminder system rather than relying on memory. The app can be part of the process, but my own calendar and budget should remain the final safety net.
A useful advanced habit is to test the payment against an ordinary month, not an unusually comfortable one. I would include rent, utilities, food, transport, existing debt, and irregular expenses before deciding. If the new obligation only works when nothing goes wrong, it is too risky for my budget.
I would also separate the purchase decision from the emotional relief of solving an urgent problem. Replacing a broken refrigerator may be necessary; upgrading a device because an offer appears may not be. Acima Leasing is more defensible when the item is genuinely needed and the complete cost is acceptable, not when the app encourages an impulse purchase.
Compared with borrowing from a bank or using a credit card, the app may be more approachable for someone who has limited traditional credit access. Compared with saving and paying cash, however, any financing route adds obligations and can cost more. Compared with a retailer’s own financing, the better option depends on the actual terms, not on the brand name or the size of the first payment.
Who should use it and who should skip it
I think Acima Leasing is best suited to a first-time applicant who has a specific necessary purchase, understands that “no credit” is not the same as “no cost,” and is willing to inspect the entire agreement. It may also suit someone who has been turned away by conventional financing and needs to explore another legitimate route.
I would skip it if I only want cash, if I do not know what I am buying, or if my budget cannot absorb another recurring obligation. I would also choose a different option when I can pay upfront without harming my emergency savings, or when a transparent bank, retailer, or credit-union offer produces a lower total cost that I can comfortably manage.
My final impression is positive but cautious. The free app from Acima gives the financing process a convenient mobile starting point, works on older supported Android devices, and has enough adoption to be familiar to many shoppers. Its real value is not making a difficult purchase feel effortless; it is helping me investigate an alternative when ordinary financing is not available.
Before proceeding, I would confirm the item, compare the complete cost, check that the payment fits a normal month, and save the agreement details. If those checks look sound, the app can be a practical next step. If they do not, walking away is the better result. That is the honest way I would recommend Acima Leasing to a friend: useful for a clearly defined need, but only when the convenience never replaces financial judgment.
Acima Leasing FAQ
What is Acima Leasing, and how does it work?
Acima Leasing is a lease-to-own service that allows eligible customers to obtain products from participating retailers without paying the full purchase price upfront. After applying and receiving approval, you make scheduled payments under a lease agreement. Depending on the agreement and applicable state rules, you may have options to buy the item early or complete the lease term.
What products can I get through Acima Leasing?
The products available through Acima Leasing depend on the participating store and may include furniture, mattresses, electronics, appliances, tires, jewelry, and other household or personal goods. Availability, pricing, and approval requirements can vary by retailer and location, so it is important to confirm that the item you want qualifies before submitting an application.
How much does Acima Leasing cost in total?
The total cost can be higher than the item’s cash price because lease-to-own agreements include scheduled lease payments and may include fees or other charges described in the contract. The amount depends on the item, payment schedule, purchase option, and applicable regulations. Review the agreement carefully and compare the early-purchase and full-term costs before accepting.
Does applying to Acima Leasing affect my credit score?
Acima Leasing may use information from your application to evaluate eligibility, and its approval process can differ from a traditional loan application. Whether an application or payment history is reported to credit bureaus depends on the current program terms and applicable policies. Read the disclosures in the application and agreement, and contact Acima directly if credit reporting is important to you.
What happens if I miss an Acima Leasing payment or want to cancel?
Missing a payment can result in late fees, collection activity, restrictions on future purchases, or other consequences stated in your lease agreement. Cancellation, returning merchandise, and early purchase options are governed by the specific contract and local law. Before downloading or applying, review the payment dates, return requirements, grace periods, and customer-support procedures so you understand your responsibilities.











